
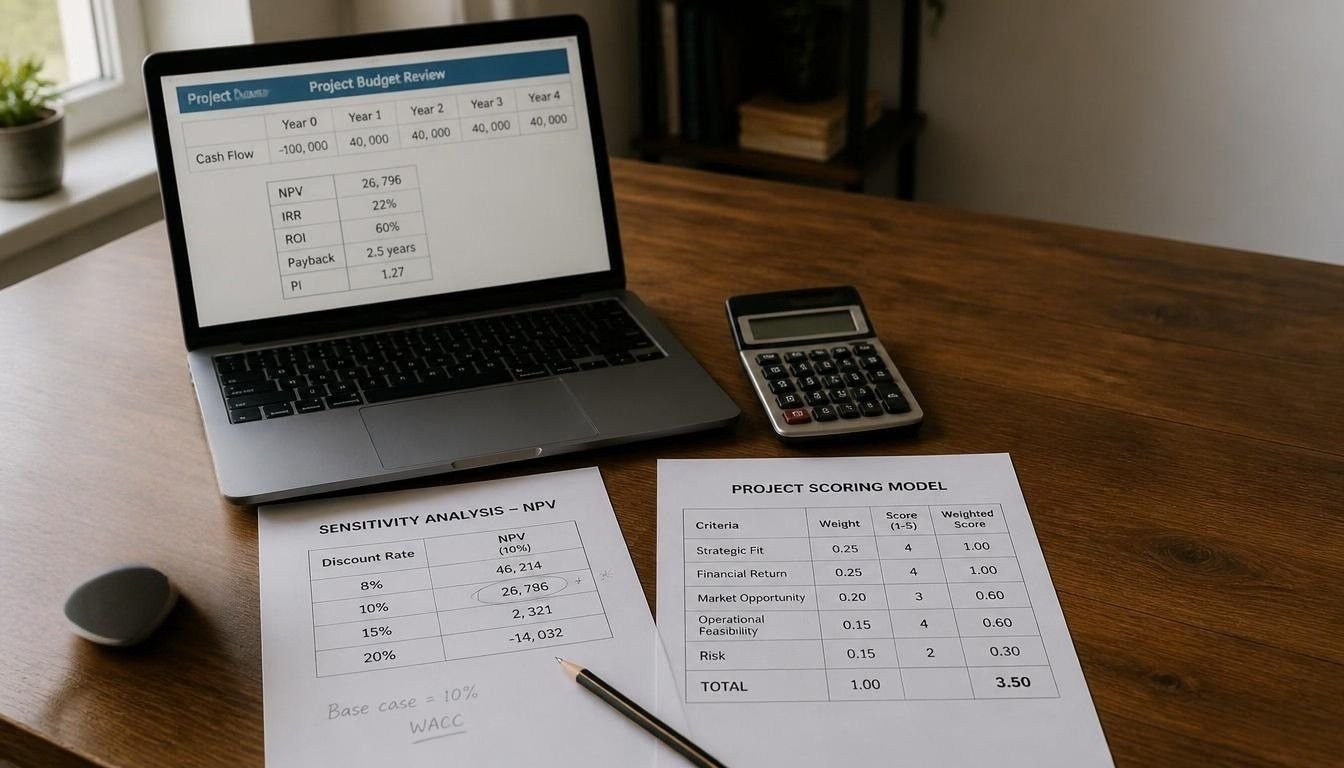
The best tool for determining value of a project depends on what you need to decide. For most investments with cash flows over several years the right choice is net present value checked against internal rate of return. For a small and fast decision ROI and payback are enough. For projects whose benefits cannot be priced in dollars a weighted scoring model works better.
Financial Value and Strategic Value Are Two Different Things
Project value comes in two forms.
Financial value is the cash a project returns after all costs. Strategic value covers benefits that are hard to price such as lower risk and stronger customer retention and regulatory compliance and added capacity.
Financial tools measure the first kind. Scoring tools help with the second. Many real decisions need both.
Project Valuation Tools Compared Side by Side
| Tool | Question it answers | Counts time value of money | Best use | Main weakness |
|---|---|---|---|---|
| ROI | How much gain do I earn per dollar spent | No | Quick screen of small projects | Ignores when cash arrives |
| Payback period | How fast do I recover my money | No | Situations where cash is tight | Ignores everything after payback |
| Net present value | How many dollars of value does this add today | Yes | Single investments with multi year cash flows | Sensitive to discount rate and forecasts |
| Internal rate of return | What annual return does the project earn | Yes | Comparing against a required return | Can mislead on project size or unusual cash flows |
| Profitability index | How much value per dollar invested | Yes | Ranking projects on a limited budget | Needs an NPV calculation first |
| Weighted scoring model | How well does it fit goals and risk | Not by itself | Projects with benefits that are hard to price | Scores can reflect bias |
How Net Present Value Works With a Worked Example
Net present value brings every future cash flow back to todays dollars and subtracts what you spend upfront. The formula is:
NPV = sum of (cash flow in year t ÷ (1 + r) to the power of t) − initial investment
Here r is your required rate of return. A positive NPV means the project earns more than that rate. A negative NPV means it earns less.
Take a small manufacturer that is considering a $100,000 packaging machine. The machine adds $40,000 in net cash each year for four years. The company requires a 10 percent return.
- Present value of the four years of cash: $126,796
- NPV: $26,796
- Payback period: 2.5 years
- Simple ROI over four years: 60 percent
- Internal rate of return: about 22 percent
- Profitability index: 1.27
The 60 percent ROI looks impressive but says nothing about timing. The NPV shows the real added value in present dollars. That is why finance teams rely on it for major spending decisions.
When NPV and IRR Disagree
IRR shows the annual return in a single percentage and that makes projects easy to compare. It can also mislead when projects differ in size.
Project X costs $10,000 and returns $15,000 after one year. Its IRR is 50 percent and its NPV at 10 percent is $3,636. Project Y costs $200,000 and returns $260,000 after one year. Its IRR is only 30 percent but its NPV at 10 percent is $36,364.
If capital is not limited Project Y adds ten times more value. If capital is limited the profitability index shows which project creates more value per dollar.
IRR can also produce more than one answer when cash flows switch between positive and negative several times. A project with a large cleanup cost at the end is a common example. In those cases rely on NPV.
Choosing a Discount Rate and Testing the Forecast
The discount rate has a large effect on the result. A common approach is to start with the weighted average cost of capital of the organization. A small business can use the return available from its next best use of money or its loan interest rate plus a premium for risk. This is general practice and not a fixed rule. Riskier projects deserve higher rates.
Never trust one rate. Run the same example at several rates:
| Discount rate | NPV of the packaging machine |
|---|---|
| 8 percent | $32,484 |
| 10 percent | $26,796 |
| 15 percent | $14,200 |
| 20 percent | $3,548 |
Then test the cash flow forecast. At a 10 percent rate this project breaks even at about $31,500 per year. Annual cash only has to fall about 21 percent short of the forecast for the value to disappear. That tells a decision maker how much room for error exists.
When Numbers Are Not Enough: Weighted Scoring Models
Some valuable projects have no clean cash flow. Think of a safety upgrade or a compliance system or a better customer portal. A weighted scoring model handles these cases.
Follow these steps:
- List the criteria that matter to the organization
- Assign each a weight that totals 100 percent
- Score every project from 1 to 5 on each criterion
- Multiply and add to get a total
A simple set of weights might be strategic fit at 30 percent and financial return at 30 percent and risk at 20 percent and resource availability at 10 percent and customer or employee impact at 10 percent.
Set the weights before you score any project. Otherwise a favorite project can quietly shape the criteria. A strong method is to shortlist by NPV first and then apply the scoring model to the shortlist.
Public sector and grant funded projects often require a formal benefit cost analysis that follows federal or state guidance. Check the funder requirements before you build the model.
Spreadsheets Versus Project Portfolio Software
A spreadsheet is a capable tool for determining value of a project when you are evaluating a handful of options. Excel and Google Sheets both include NPV and IRR and XNPV and XIRR and MIRR functions. XNPV and XIRR use exact dates and suit uneven cash flows.
One detail catches many users. The NPV function treats the first value as arriving at the end of period one. Enter the upfront cost outside the function and subtract it. The formula looks like this: NPV of the rate and the inflows minus the initial cost.
Dedicated project portfolio management software becomes useful when many projects compete for shared budgets and people. It adds side by side ranking and scenario planning and resource tracking. It still depends on the same formulas and the same forecast quality.
Which Valuation Tool Fits Your Project: A Decision Framework
Five factors should drive your choice:
- Size and duration: Larger and longer projects need discounted cash flow methods
- Data quality: Weak forecasts make complex models look more precise than they are
- Priceable benefits: If you cannot put dollars on the benefits add a scoring model
- Budget limits: A fixed budget calls for the profitability index
- Audience: Lenders and boards usually expect NPV and IRR and payback together
| Your situation | Use this | Why |
|---|---|---|
| Small low cost idea with fast results | ROI and payback | Fast and good enough when little money is at risk |
| One major investment with multi year cash flows | NPV checked with IRR | Counts timing and shows the dollar value added |
| Several projects and a fixed budget | Profitability index then scoring | Ranks value per dollar and then adds strategy |
| Benefits are hard to price | Weighted scoring model | Captures strategy and risk without false precision |
| Highly uncertain forecasts | NPV under best and expected and worst cases | Shows how much error the project can survive |
If you are unsure which tool for determining value of a project to start with begin with NPV. It is the most widely accepted financial measure and the easiest to defend in front of a finance team.
Understand the trade offs. Payback favors fast returns and can reject projects with excellent long term value. IRR favors small and short projects. Scoring models add judgment and judgment brings bias. No tool removes the need to question the assumptions.
Common Mistakes That Distort Project Valuation
- Using revenue instead of incremental net cash flow
- Counting sunk costs that cannot be recovered
- Leaving out ongoing costs such as maintenance and training and added working capital
- Ignoring taxes. US federal corporate income tax is 21 percent and state taxes can add more. Use after tax cash flows and confirm depreciation treatment with a tax professional
- Applying one discount rate to projects with very different risk
- Forgetting the end of the project such as resale value or disposal cost
- Skipping the comparison with simply doing nothing or choosing another use for the money
A Practical Sequence for Valuing Your Next Project
- Define the decision and the alternatives including doing nothing.
- Estimate incremental after tax cash flows for each year of the project life.
- Choose a discount rate that reflects the risk of the project.
- Calculate NPV and IRR and payback and profitability index.
- Test the result at higher discount rates and lower cash inflows.
- Score non financial factors for the projects that pass.
- Document the assumptions so the decision can be reviewed later.
FAQs
What is the best tool for determining value of a project?
Net present value is the best starting point for most investments because it counts timing and risk and gives a dollar result. Pair it with IRR and a sensitivity test. Add a weighted scoring model when important benefits cannot be priced.
Is ROI enough to value a project?
ROI works as a quick first screen but it ignores when the cash arrives. A project that returns money in year five can show the same ROI as one that returns money in year one. Use NPV for any project that lasts more than a year.
What discount rate should I use?
Use the cost of capital of your organization as a starting point and raise it for riskier projects. Small businesses can use the return on the next best alternative or loan interest plus a risk premium. Always test several rates.
How do I value a project when the benefits are hard to measure
Use a weighted scoring model with criteria set in advance. You can also estimate a cost for the problem the project solves such as the cost of downtime or turnover or penalties. Label these as estimates in your analysis.
Is a spreadsheet a good tool for determining value of a project?
Yes for most small and medium decisions. Excel and Google Sheets calculate NPV and IRR accurately. The main risks are formula errors and weak assumptions. Have a second person review the model before you rely on it.
What should I do when NPV and IRR give different rankings?
Trust NPV when capital is not limited because it shows total value added. When the budget is limited compare the profitability index. Differences usually come from project size and timing.