
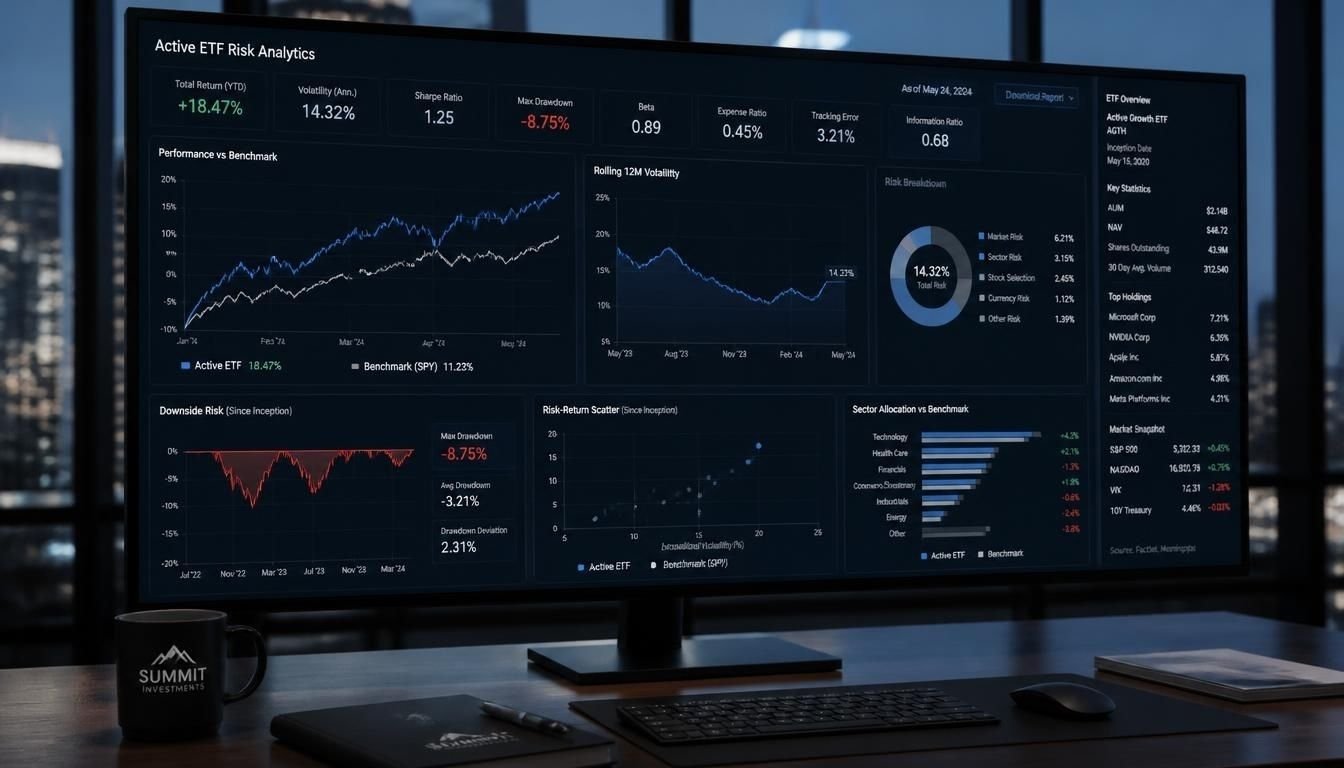
An actively managed exchange-traded fund does more than follow a predefined market index. Its portfolio manager makes investment decisions involving security selection, sector allocation, portfolio weighting and market exposure.
These decisions create opportunities for additional returns but also introduce risks that investors need to evaluate.
Active ETF risk metrics help investors understand how much volatility a fund experiences, how it responds to market movements, how consistently it performs against a benchmark and how much capital investors could lose during unfavorable conditions.
Unlike passive ETFs that primarily aim to replicate an index, active ETFs depend partly on the investment strategy and decisions of their portfolio managers. This makes it important to evaluate both traditional investment risk measures and metrics designed to assess active management.
A complete evaluation should answer four important questions:
- How much can the ETF’s value fluctuate?
- What could happen during a market downturn?
- Is the portfolio manager generating returns efficiently?
- Can investors buy or sell shares without excessive trading costs?
Understanding these areas provides a more realistic picture of an ETF’s investment risks.
Key Takeaways
- Active ETFs require more than basic volatility analysis because portfolio managers make ongoing investment decisions that can change risk exposure.
- Standard deviation and beta measure overall volatility and sensitivity to market movements.
- Sharpe ratio and Sortino ratio help investors understand whether returns justify the risks taken.
- Tracking error and information ratio reveal how an active ETF performs relative to its benchmark.
- Liquidity, concentration, maximum drawdown and portfolio holdings help identify risks that performance figures may overlook.
Which Risk Metrics Matter Most for Active ETFs?
No single measurement captures every type of investment risk. Investors should examine several metrics together because each measures a different aspect of portfolio behavior.
1. Standard Deviation
Standard deviation measures how much an ETF’s returns fluctuate around their average return over a particular period.
A higher standard deviation indicates greater historical volatility. A lower reading suggests that returns have generally experienced smaller fluctuations.
For example:
Consider two hypothetical actively managed equity ETFs.
| Measurement | ETF A | ETF B |
|---|---|---|
| Annualized return | 12% | 10% |
| Standard deviation | 18% | 11% |
| Investment approach | Growth focused | Diversified |
ETF A generated a higher return but experienced considerably greater volatility.
ETF B delivered a lower return with a more stable historical performance pattern.
This does not automatically make ETF B the better investment. An investor with a longer investment horizon and greater tolerance for volatility may prefer ETF A.
What investors should evaluate:
- Compare standard deviation over identical periods.
- Examine monthly or weekly return data when available.
- Compare the ETF with funds following similar strategies.
- Check whether volatility increased during market downturns.
- Avoid interpreting low volatility as protection against losses.
Standard deviation measures both positive and negative fluctuations. It does not distinguish between favorable price movements and damaging declines.
2. Beta
Beta measures how sensitive an ETF is to movements in a selected market benchmark.
The benchmark is assigned a beta of 1.00.
| Beta Reading | General Interpretation |
|---|---|
| Above 1.00 | Historically more sensitive to benchmark movements |
| Around 1.00 | Historically similar sensitivity |
| Between 0 and 1.00 | Historically less sensitive |
| Below 0 | Historically moved in the opposite direction |
For example, an ETF with a beta of 1.25 has historically shown greater sensitivity to movements in its benchmark.
If the benchmark rises or falls by 1% under the relationship estimated by the model, the ETF would be expected to move approximately 1.25% in the same direction.
This is a statistical relationship rather than a prediction.
Why beta matters for active ETFs
Portfolio managers can increase or reduce market exposure through security selection, sector allocation and other investment decisions.
A growth-oriented active ETF may have higher market sensitivity than a diversified strategy.
However, beta has limitations. It does not fully capture risks arising from individual securities, changing correlations, derivatives or unusual market conditions.
Investors should also check whether the selected benchmark accurately represents the ETF’s investment strategy.
3. Sharpe Ratio
The Sharpe ratio measures excess investment return relative to total volatility.
It helps investors evaluate how efficiently an ETF has historically generated returns compared with the risk-free rate.
The formula is:
\[ \text{Sharpe Ratio} = \frac{R_p-R_f}{\sigma_p} \]
Where:
- \(R_p\) = ETF return
- \(R_f\) = Risk-free rate
- \(\sigma_p\) = Standard deviation of ETF returns
Consider an ETF with an annualized return of 12%, a risk-free rate of 4% and annualized standard deviation of 16%.
Its Sharpe ratio would be:
\[ \frac{12-4}{16}=0.50 \]
A higher Sharpe ratio generally indicates better historical compensation for total volatility.
However, investors should avoid treating a particular reading as a universal buying threshold.
The result depends on the measurement period, return frequency, risk-free rate and market environment.
When to use it:
- Comparing active ETFs with similar investment objectives.
- Evaluating risk-adjusted performance.
- Examining whether higher returns required substantially greater volatility.
- Comparing portfolio strategies over consistent periods.
The Sharpe ratio is particularly useful when investors want to understand overall portfolio efficiency rather than simply identifying the fund with the highest return.
4. Sortino Ratio
The Sortino ratio is similar to the Sharpe ratio but focuses on downside volatility rather than all return fluctuations.
This distinction matters because investors may not consider positive price movements a meaningful investment risk.
The formula is:
\[ \text{Sortino Ratio} = \frac{R_p-R_f}{D} \]
Where:
- \(R_p\) = ETF return
- \(R_f\) = Risk-free rate
- \(D\) = Downside deviation
For example, two active ETFs could have similar average returns but different downside behavior.
One may experience frequent losses while the other maintains relatively stable performance during unfavorable periods.
The Sortino ratio helps identify this difference.
Why investors should consider it
- It focuses specifically on unfavorable return movements.
- It provides additional information alongside standard deviation.
- It can help compare strategies with different downside characteristics.
- It is useful when capital preservation is an important investment objective.
One limitation is that the result depends on the minimum acceptable return selected for calculating downside deviation.
Investors should check the calculation methodology before comparing funds.
Measuring Active Management Performance Against a Benchmark
Traditional volatility measurements explain how an ETF behaves in the market. However, active investors also need to evaluate whether the fund manager’s decisions are adding value.
This requires examining benchmark-relative performance.
5. Tracking Error
Tracking error measures the variability of an ETF’s returns relative to a selected benchmark.
It is calculated as the annualized standard deviation of the difference between ETF returns and benchmark returns.
\[ TE=\sigma(R_p-R_b) \]
Where:
- \(R_p\) = ETF return
- \(R_b\) = Benchmark return
- \(TE\) = Tracking error
Tracking error is commonly associated with passive ETFs because these funds aim to follow an index.
For active ETFs, however, it has a different interpretation.
A higher tracking error can indicate that the manager is taking substantial active positions away from the benchmark.
This may be intentional rather than a sign of poor management.
For example:
An active technology ETF may hold different companies and sector weightings from a broad US equity benchmark.
Its performance could therefore move differently from the benchmark even when the investment strategy is working as intended.
What investors should understand:
- Low tracking error indicates relatively similar return behavior to the benchmark.
- High tracking error indicates greater variability in benchmark-relative returns.
- High tracking error does not automatically indicate excessive risk.
- The ETF’s investment objective determines whether benchmark deviations are appropriate.
Investors should also distinguish tracking error from tracking difference.
Tracking difference represents the actual return gap between the ETF and benchmark over a specific period. Tracking error measures how variable that gap has been.
6. Information Ratio
The information ratio evaluates how efficiently an active ETF generates returns above its benchmark relative to its active risk.
It is calculated using:
\[ IR=\frac{R_p-R_b}{TE} \]
Where:
- \(R_p-R_b\) = Active return
- \(TE\) = Tracking error
Consider two hypothetical active ETFs.
| Measurement | ETF A | ETF B |
|---|---|---|
| Annualized active return | 3% | 2% |
| Tracking error | 6% | 3% |
| Information ratio | 0.50 | 0.67 |
ETF A generated greater benchmark-relative returns.
However, ETF B generated more active return relative to the amount of active risk taken.
This illustrates why investors should not evaluate active managers using outperformance alone.
When information ratio is useful:
- Comparing active managers following similar strategies.
- Evaluating the consistency of benchmark-relative performance.
- Identifying whether active risk has generated meaningful additional returns.
- Reviewing investment strategies over multiple market environments.
A higher information ratio can indicate more efficient active management, but it does not guarantee future performance.
The selected benchmark must also be appropriate for the fund’s strategy.
7. Alpha
Alpha measures investment performance beyond the return expected from exposure to market risk under a particular asset pricing model.
In traditional analysis, Jensen’s alpha is commonly associated with the Capital Asset Pricing Model.
A simplified formula is:
\[ \alpha=R_p-[R_f+\beta(R_m-R_f)] \]
Where:
- \(R_p\) = Portfolio return
- \(R_f\) = Risk-free rate
- \(\beta\) = Portfolio beta
- \(R_m\) = Market return
A positive alpha suggests that the ETF outperformed the return predicted by the model.
A negative alpha indicates underperformance relative to that expectation.
For active ETFs, alpha can help investors examine whether portfolio management has contributed additional performance beyond broad market exposure.
However, alpha should not automatically be interpreted as proof of investment manager skill.
Results can be affected by:
- The selected benchmark.
- The evaluation period.
- Market conditions.
- Portfolio factor exposures.
- Management fees and other expenses.
- Statistical estimation limitations.
Investors should examine alpha alongside information ratio, Sharpe ratio and portfolio attribution.
Measuring Potential Losses During Market Downturns
Historical returns can look attractive even when an ETF has experienced substantial losses along the way.
Downside risk measurements provide additional information about the potential severity of unfavorable investment periods.
8. Maximum Drawdown
Maximum drawdown measures the largest percentage decline from a portfolio’s previous peak to its subsequent lowest point during a selected period.
The formula is:
\[ MDD=\frac{T-P}{P}\times100 \]
Where:
- \(P\) = Previous portfolio peak
- \(T\) = Subsequent trough
For example, suppose an active ETF increases to $100 per share before declining to $75.
Its maximum drawdown during that decline is 25%.
This metric helps investors understand the historical severity of losses rather than focusing only on annualized returns.
What to examine:
- Maximum drawdown over three and five years where available.
- The duration of the decline.
- The time required to recover the previous peak.
- Performance during major market downturns.
- Whether losses were concentrated in particular sectors or holdings.
Maximum drawdown is especially useful for investors who may need access to their capital during unfavorable market conditions.
However, historical drawdowns cannot establish the maximum amount an investor could lose in the future.
9. Value at Risk
Value at Risk or VaR estimates the potential loss of a portfolio over a specified period at a selected confidence level.
For example, a one-day 95% VaR of $10,000 means that the model estimates a 5% probability of losing more than $10,000 over one day under its assumptions.
This does not mean the maximum possible loss is $10,000.
Actual losses can exceed the estimated VaR.
Investors should understand three important components:
- Time horizon: The period over which potential losses are estimated.
- Confidence level: The statistical confidence selected for the calculation.
- Calculation method: Historical simulation, parametric modeling or Monte Carlo simulation.
VaR is more commonly used in institutional risk management and portfolio analysis than in basic retail ETF comparisons.
It can provide additional insight into portfolio exposure, but investors should not rely on it alone because it does not adequately describe the severity of losses beyond the selected threshold.
10. Conditional Value at Risk
Conditional Value at Risk or CVaR is also known as Expected Shortfall.
It estimates the average loss within the worst outcomes beyond a selected VaR threshold.
For example, while VaR identifies a loss threshold associated with a particular confidence level, CVaR helps estimate the average loss when that threshold is exceeded.
This distinction is important for active ETFs holding:
- Concentrated equity positions.
- Lower-liquidity securities.
- High-yield bonds.
- Complex derivatives.
- Assets exposed to significant market fluctuations.
CVaR can provide a more detailed view of extreme downside exposure than VaR alone.
However, it remains dependent on the quality of the underlying data and assumptions.
Portfolio Concentration and Holdings Risk
An ETF can have relatively low historical volatility while still carrying significant concentration risk.
This is particularly important for actively managed funds because portfolio managers can allocate substantial capital to selected companies or industries.
11. Portfolio Concentration
Portfolio concentration measures how much of an ETF’s assets are invested in a limited number of securities, sectors or other exposures.
Investors should examine:
- Percentage allocated to the largest holding.
- Combined allocation to the top five and ten holdings.
- Sector weightings.
- Industry exposure.
- Geographic allocation.
- Exposure to individual investment themes.
For example, an active equity ETF may hold 30 companies but allocate 45% of its assets to its five largest positions.
Although the fund owns multiple securities, its performance may depend heavily on a relatively small group of companies.
This creates additional company-specific and concentration risks.
12. Active Share
Active share measures how different an actively managed portfolio’s holdings are from those of its benchmark.
It is generally calculated by comparing portfolio weights with benchmark weights.
\[ AS=\frac{1}{2}\sum_{i=1}^{N}|w_{p,i}-w_{b,i}| \]
Where:
- \(w_{p,i}\) = Portfolio weight of security \(i\)
- \(w_{b,i}\) = Benchmark weight of security \(i\)
A higher active share indicates greater differences between the ETF’s holdings and its benchmark.
For example:
An ETF with an active share of 80% has portfolio weights that differ substantially from the benchmark.
An ETF with an active share of 30% has holdings that are relatively closer to the benchmark.
Active share is not a direct measure of volatility or downside risk.
It describes portfolio differentiation.
A high active share can create opportunities for differentiated returns but may also introduce greater stock-specific and portfolio deviation risks.
Investors should use it alongside concentration, beta, tracking error and downside measurements.
Liquidity Risk and ETF Trading Costs
Active ETFs trade on US stock exchanges throughout the trading day.
However, an ETF’s ability to trade efficiently depends on more than its average daily trading volume.
The liquidity of the underlying securities also matters.
13. Bid-Ask Spread
The bid-ask spread is the difference between the highest price a buyer is willing to pay and the lowest price a seller is willing to accept.
For example:
| Trading Information | Amount |
|---|---|
| Bid price | $49.95 |
| Ask price | $50.05 |
| Bid-ask spread | $0.10 |
| Midpoint | $50.00 |
| Percentage spread | 0.20% |
A wider spread generally means higher transaction costs.
Investors should examine spreads over different trading sessions rather than relying on one price quote.
Spreads can widen during:
- Market volatility.
- Low trading activity.
- The opening and closing periods.
- Trading in less liquid underlying securities.
- Unexpected market announcements.
For investors making larger transactions, the spread can have a meaningful impact on the effective purchase or selling price.
14. Average Daily Trading Volume
Average daily trading volume measures the number of ETF shares traded over a specified period.
Higher volume can indicate stronger secondary-market trading activity.
However, volume alone does not determine an ETF’s complete liquidity.
An ETF with relatively low trading volume may still have access to liquidity through its underlying holdings and the ETF creation and redemption process.
Investors should examine:
- Average daily trading volume.
- Average bid-ask spread.
- Assets under management.
- Liquidity of underlying securities.
- Market depth.
- Premiums and discounts to net asset value.
15. Premium and Discount to NAV
An ETF’s market price can differ from its net asset value per share.
The net asset value represents the value of the fund’s assets minus its liabilities divided by the number of outstanding shares.
An ETF trading above NAV is at a premium.
An ETF trading below NAV is at a discount.
The percentage difference can be calculated as:
\[ \text{Premium or Discount}= \frac{\text{Market Price}-NAV}{NAV}\times100 \]
For example, if an ETF has a NAV of $100 and trades at $101, it has a 1% premium.
Investors should examine whether premiums and discounts are temporary or persistent.
This is particularly important for active ETFs investing in international securities, corporate bonds and other assets that may not have continuously updated market prices.
A premium or discount does not automatically indicate poor fund management. It can also reflect market conditions, underlying asset liquidity and differences in pricing times.
Important Active ETF Risk Metrics
The following table summarizes the primary measurements investors should understand when evaluating an actively managed ETF.
| Risk Metric | What It Measures | Main Purpose |
|---|---|---|
| Standard Deviation | Return volatility | Evaluate overall fluctuations |
| Beta | Market sensitivity | Understand benchmark exposure |
| Sharpe Ratio | Return per unit of total risk | Evaluate risk-adjusted performance |
| Sortino Ratio | Return per unit of downside risk | Assess downside efficiency |
| Tracking Error | Volatility of active returns | Measure benchmark deviation |
| Information Ratio | Active return per unit of active risk | Evaluate active management efficiency |
| Alpha | Model-adjusted excess performance | Assess additional returns |
| Maximum Drawdown | Largest peak-to-trough decline | Understand historical losses |
| Value at Risk | Estimated loss threshold | Examine modeled downside exposure |
| Conditional VaR | Average loss beyond the VaR threshold | Evaluate extreme downside risk |
| Active Share | Difference in portfolio holdings from benchmark | Measure portfolio differentiation |
| Bid-Ask Spread | Difference between buying and selling quotes | Estimate trading costs |
| Average Daily Volume | Average number of shares traded | Assess trading activity |
| Premium or Discount | Market price difference from NAV | Examine ETF pricing |
No individual metric provides a complete picture of investment risk. Combining these measurements helps investors evaluate portfolio behavior, management decisions and trading conditions.
How to Compare Two Active ETFs Using Risk Metrics
Comparing active ETFs requires more than placing their annualized returns side by side.
Two funds can follow similar investment objectives while maintaining very different portfolio exposures and risk characteristics.
A practical comparison should follow a consistent process.
Step 1. Confirm That Both ETFs Have Similar Objectives
Start by examining the investment strategy of each fund.
Check whether they invest in:
- Large-cap US equities.
- Small-cap companies.
- Growth or value stocks.
- Corporate bonds.
- International securities.
- Sector-specific investments.
- Multi-asset portfolios.
Comparing funds with different investment objectives can produce misleading conclusions.
Step 2. Compare Historical Volatility
Review standard deviation and beta over identical periods.
For example, compare both funds using three-year annualized measurements if sufficient history is available.
Look for differences in market sensitivity and historical fluctuations.
Step 3. Evaluate Downside Performance
Examine maximum drawdown and Sortino ratio.
These measurements help identify how the funds behaved during unfavorable periods.
Also review the recovery period after major declines.
Step 4. Review Active Management Efficiency
Compare information ratio, alpha and tracking error.
The objective is to understand whether the manager’s active investment decisions have generated additional returns relative to the benchmark.
A fund with higher returns is not necessarily more efficient if it required substantially greater active risk.
Step 5. Examine Portfolio Holdings
Review the latest holdings and portfolio allocation.
Check whether one fund has greater exposure to a particular company, industry or investment theme.
This is important because historical performance statistics may not fully reflect recent changes in portfolio construction.
Step 6. Evaluate Trading Costs
Finally, compare bid-ask spreads, underlying asset liquidity and premiums or discounts to NAV.
An ETF with strong historical performance may still be less suitable if its trading conditions create significant costs.
Expert Decision-Making: Which Active ETF Risk Metrics Should You Prioritize?
The most useful risk measurements depend on the investor’s objectives, investment horizon and tolerance for losses.
Rather than treating every metric equally, investors should prioritize the measurements that address their biggest investment concerns.
For Investors Focused on Capital Preservation
Prioritize:
- Maximum drawdown.
- Sortino ratio.
- Standard deviation.
- Portfolio concentration.
- Conditional Value at Risk.
These measurements help examine downside exposure and the severity of historical losses.
However, none guarantees that future losses will remain within historical ranges.
For Investors Seeking Long-Term Growth
Prioritize:
- Standard deviation.
- Beta.
- Sharpe ratio.
- Maximum drawdown.
- Sector and company concentration.
Growth-oriented strategies may experience greater fluctuations.
The important question is whether the portfolio’s potential return characteristics justify its risk exposure.
For Investors Evaluating Active Fund Managers
Prioritize:
- Information ratio.
- Alpha.
- Tracking error.
- Active share.
- Portfolio attribution.
These measurements help distinguish benchmark-relative performance from general market movements.
Investors should also evaluate the manager’s investment process, consistency and changes in portfolio strategy.
For Investors Making Large ETF Transactions
Prioritize:
- Bid-ask spread.
- Underlying asset liquidity.
- Market depth.
- Premium or discount to NAV.
- Average daily trading volume.
These factors help estimate transaction costs and potential execution difficulties.
A fund with lower screen volume is not automatically illiquid. Its underlying holdings and primary-market activity can provide additional liquidity.
A Practical Risk Evaluation Framework
| Investor Priority | First Metrics to Examine | Additional Checks |
|---|---|---|
| Lower volatility | Standard deviation and beta | Maximum drawdown |
| Downside protection | Sortino ratio and maximum drawdown | CVaR |
| Manager performance | Information ratio and alpha | Active share |
| Benchmark deviation | Tracking error | Active return |
| Portfolio diversification | Concentration and active share | Sector exposure |
| Trading efficiency | Bid-ask spread | NAV premium or discount |
The strongest evaluation combines historical performance, portfolio construction and current trading conditions.
Investors should also examine the fund’s prospectus, latest shareholder report and official holdings information before making an investment decision.
Common Mistakes When Evaluating Active ETF Risk
Even experienced investors can misinterpret investment measurements when they examine them individually.
Several common mistakes can lead to incomplete risk assessments.
Choosing an ETF Based Only on Its Sharpe Ratio
A higher Sharpe ratio indicates better historical return relative to total volatility.
However, it does not explain portfolio concentration, liquidity conditions or extreme downside exposure.
Always examine additional measurements.
Treating High Tracking Error as Poor Management
Active ETFs are designed to make investment decisions that can differ from benchmark allocations.
High tracking error may reflect intentional portfolio positioning.
Its significance depends on whether those decisions align with the fund’s stated strategy.
Ignoring Changes in Portfolio Holdings
Historical risk measurements are based on past portfolio behavior.
An ETF that recently changed its investment approach may have a different risk profile from the one reflected in its historical statistics.
Review current holdings and portfolio disclosures.
Using Average Daily Volume as the Only Liquidity Measurement
ETF liquidity also depends on the securities held inside the fund.
A low-volume ETF with liquid underlying assets may still be tradable at reasonable prices.
Examine bid-ask spreads, underlying liquidity and market conditions together.
Comparing Different Time Periods
A one-year Sharpe ratio should not be compared directly with a five-year Sharpe ratio without considering the different measurement periods.
Market conditions can significantly affect volatility and risk-adjusted returns.
Use consistent periods whenever possible.
Assuming Historical Risk Predicts Future Losses
Historical metrics describe previous market behavior.
They cannot guarantee future volatility, returns or maximum losses.
Investment strategies, market conditions and portfolio holdings can change.
FAQs About Active ETF Risk Metrics
1. What are the most important active ETF risk metrics?
The most important active ETF risk metrics include standard deviation, beta, Sharpe ratio, Sortino ratio, tracking error, information ratio and maximum drawdown.
Investors should also examine portfolio concentration, active share and liquidity measurements to understand risks beyond historical returns.
2. How does tracking error affect active ETFs?
Tracking error measures how much an ETF’s returns fluctuate relative to its benchmark.
A higher reading indicates greater variability in benchmark-relative performance. For active ETFs, this may reflect intentional investment decisions rather than poor tracking.
3. What is a good Sharpe ratio for an active ETF?
There is no universally appropriate Sharpe ratio for every active ETF.
A higher reading generally indicates better historical risk-adjusted performance. However, investors should compare funds with similar strategies and examine consistent measurement periods.
4. Is a higher beta riskier for an active ETF?
A higher beta indicates greater historical sensitivity to movements in the selected benchmark.
This can result in larger fluctuations when the benchmark rises or falls. However, beta does not capture every source of portfolio risk.
5. What is the difference between Sharpe ratio and Sortino ratio?
The Sharpe ratio considers total return volatility, including positive and negative fluctuations.
The Sortino ratio focuses on downside deviation. It can therefore provide additional insight for investors particularly concerned about unfavorable returns.
6. Why is maximum drawdown important when evaluating active ETFs?
Maximum drawdown shows the largest historical decline from a previous portfolio peak to a subsequent trough.
It helps investors understand the severity of past losses and evaluate whether the fund’s historical downside behavior matches their investment tolerance.
7. Does active share measure investment risk?
Active share measures how different an ETF’s portfolio holdings are from its benchmark.
It is not a direct measure of volatility or potential losses. However, higher active share can indicate greater portfolio differentiation and potentially more security-specific risk.
8. How can investors evaluate liquidity risk in active ETFs?
Investors should examine average bid-ask spreads, trading volume, underlying asset liquidity, market depth and premiums or discounts to NAV.
These measurements provide a more complete picture of how efficiently ETF shares can be traded.
9. Are active ETFs riskier than passive ETFs?
Not necessarily.
Risk depends on the underlying investments, portfolio construction, diversification, investment strategy and use of financial instruments.
An actively managed ETF may carry higher or lower risk than a passive ETF depending on its actual holdings and exposures.
10. How often should investors review active ETF risk metrics?
Investors should review risk measurements periodically and whenever significant changes occur in market conditions, portfolio holdings or investment strategy.
Quarterly reviews can provide a useful starting point for long-term investors, while more frequent monitoring may be appropriate for concentrated or complex strategies.
The frequency should reflect the investment objective rather than follow a universal schedule.